Last week’s inflation reports came in hot. September’s CPI rose 0.6% m/m, lifting headline inflation from 3.4% y/y in August to 3.7%. Core CPI rose 0.3% m/m, taking its y/y rate from 2.4% to 2.6%. Both topped expectations. PPI final demand jumped 1.3% m/m. That pushed its y/y rate to 6.3%, the highest since 2022. Retail sales rose 0.8% m/m, though just 0.2% excluding gas stations.
Odds of a 25bps hike at the October 27-28 FOMC meeting fell from 22% before the CPI report to 17%, despite the hot inflation data. Fed Chair Kevin Warsh offered no signal on October's meeting at the IMF and World Bank annual meetings in Bangkok on Friday. “I don’t prejudge meetings,” he said. Odds of a December hike rose. We still expect the Fed to reverse the remaining two of last year’s three 25bps “insurance” cuts. Fed officials are now in their pre-meeting blackout period.
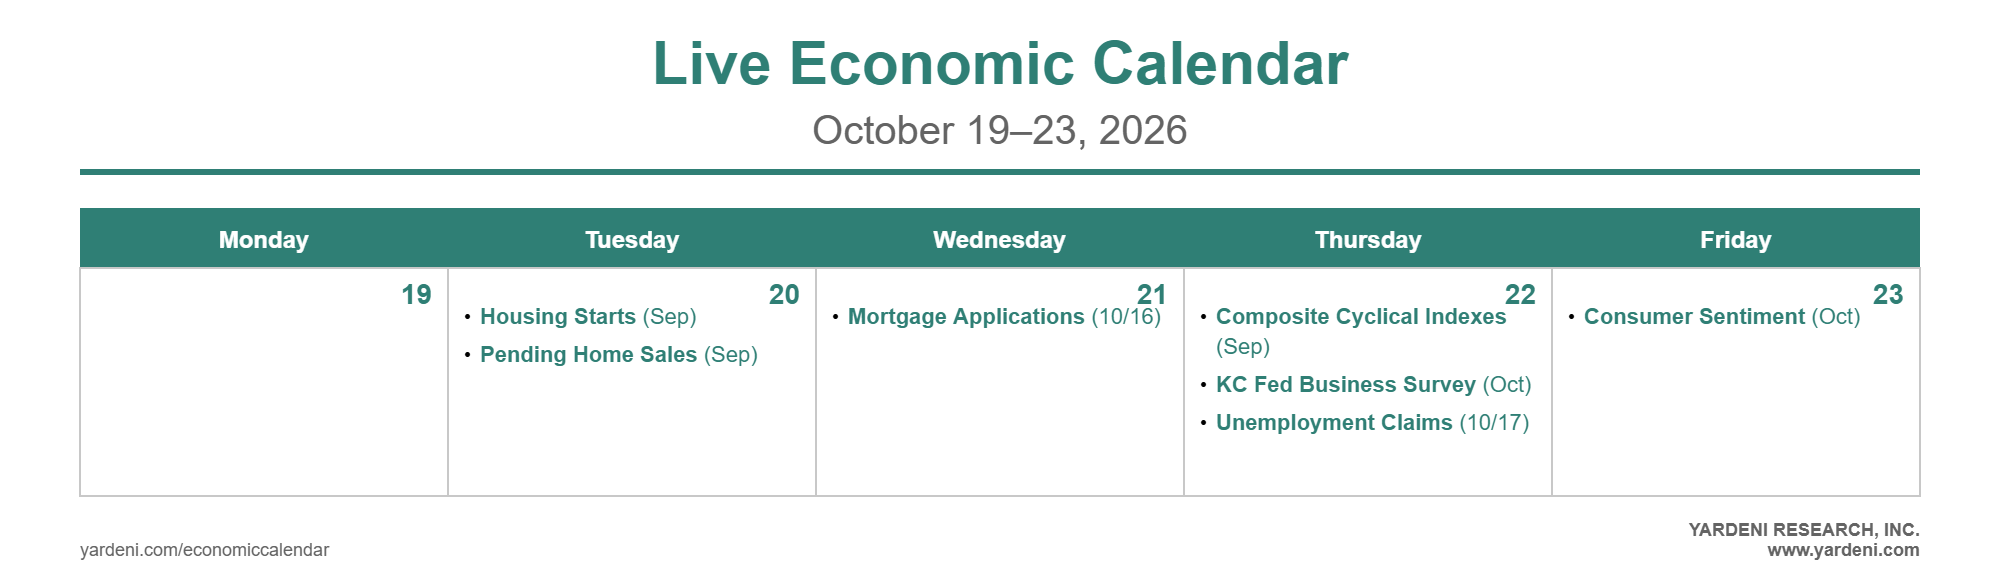
This week’s data calendar is light, with earnings season taking center stage. Friday’s flash PMIs are the main US releases. The Fed’s Financial Stability Report and Canada’s federal budget are tentatively due Tuesday. Here’s more:
(1) ADP & Unemployment Claims. ADP’s weekly employment reading (Tue) follows a rise in the four-week average to 24,750 for the week ended September 26, the highest since early June and up from a late-July bottom of 8,250 (chart).
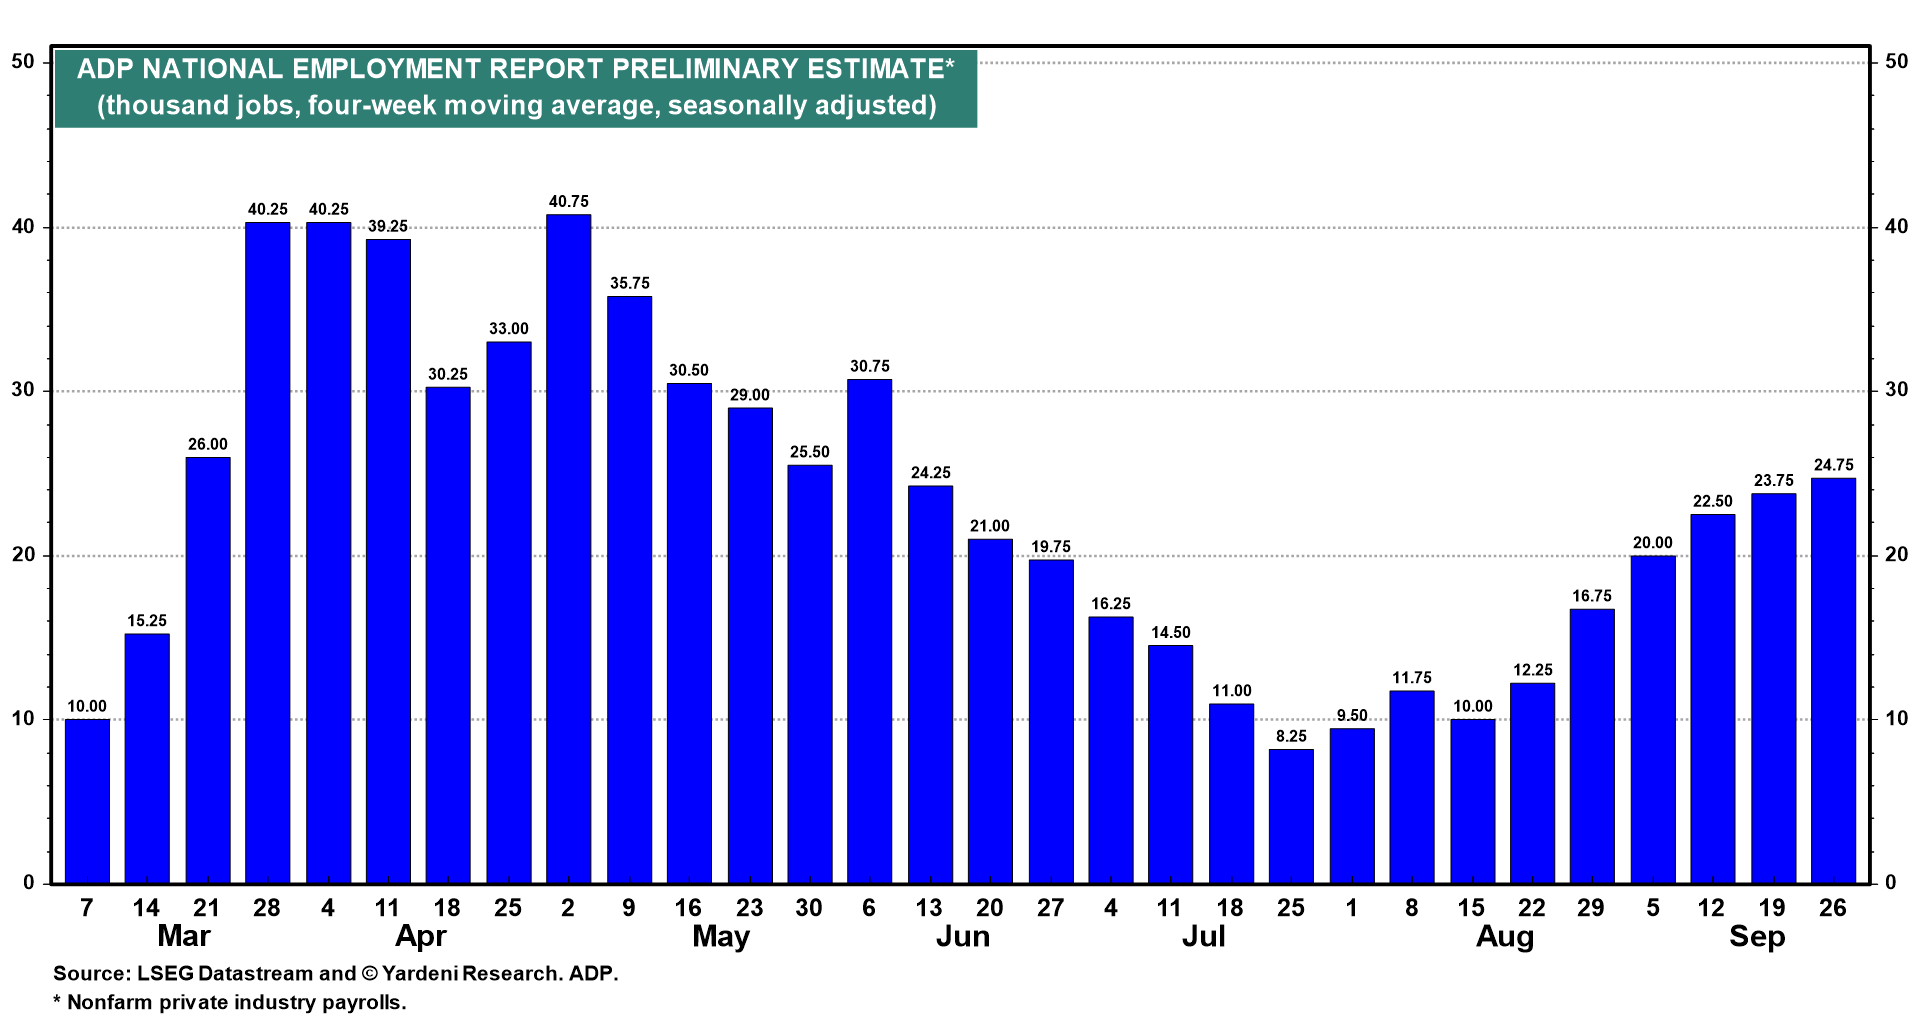
Initial jobless claims (Thu) follow last week’s 199,000, with the four-week average at 198,500 (chart). Continuing claims fell to 1,710,000 for the week ended October 2, matching their four-week average. The labor market continues to improve.
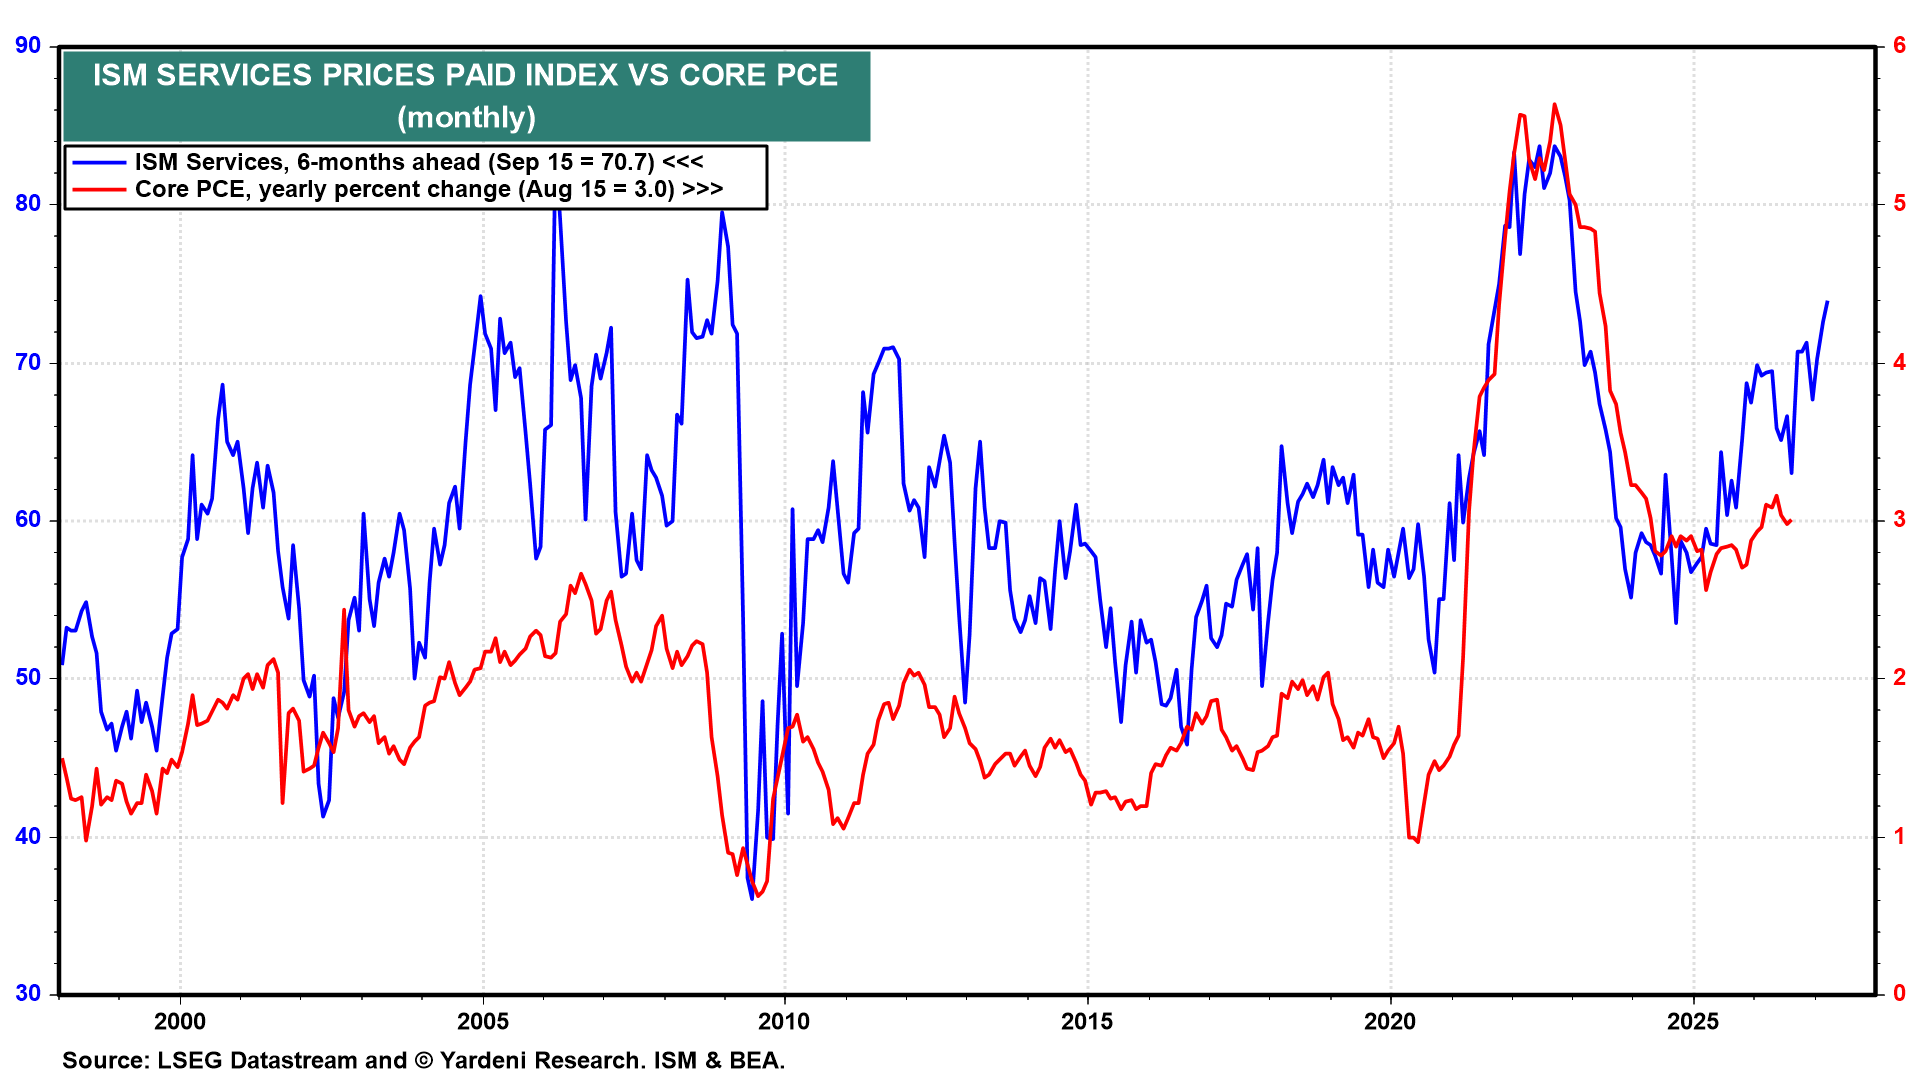
(2) Flash PMIs. S&P Global’s flash M-PMI and NM-PMI for October (Fri) follow September readings of 55.9 and 58.8 (chart). The services prices component is worth watching after ISM’s NM-PMI prices-paid index jumped to 70.7 in September, the highest since July 2022.
Flash PMIs for Australia and Japan (Thu) and for the Eurozone, Germany, France, and the UK (Fri) also land this week. September’s M-PMIs were 52.9 for the Eurozone and 52.1 for the UK.
(3) Earnings. The earnings reporting season picks up this week. Netflix, GE Aerospace, and Northrop Grumman report on Tuesday. Tesla and Meta, the first of the Magnificent-7 to report, follow on Wednesday along with Lam Research, IBM, and Texas Instruments. Spotify, Bloom Energy, Western Digital, Lockheed Martin, and Blackstone report on Thursday.
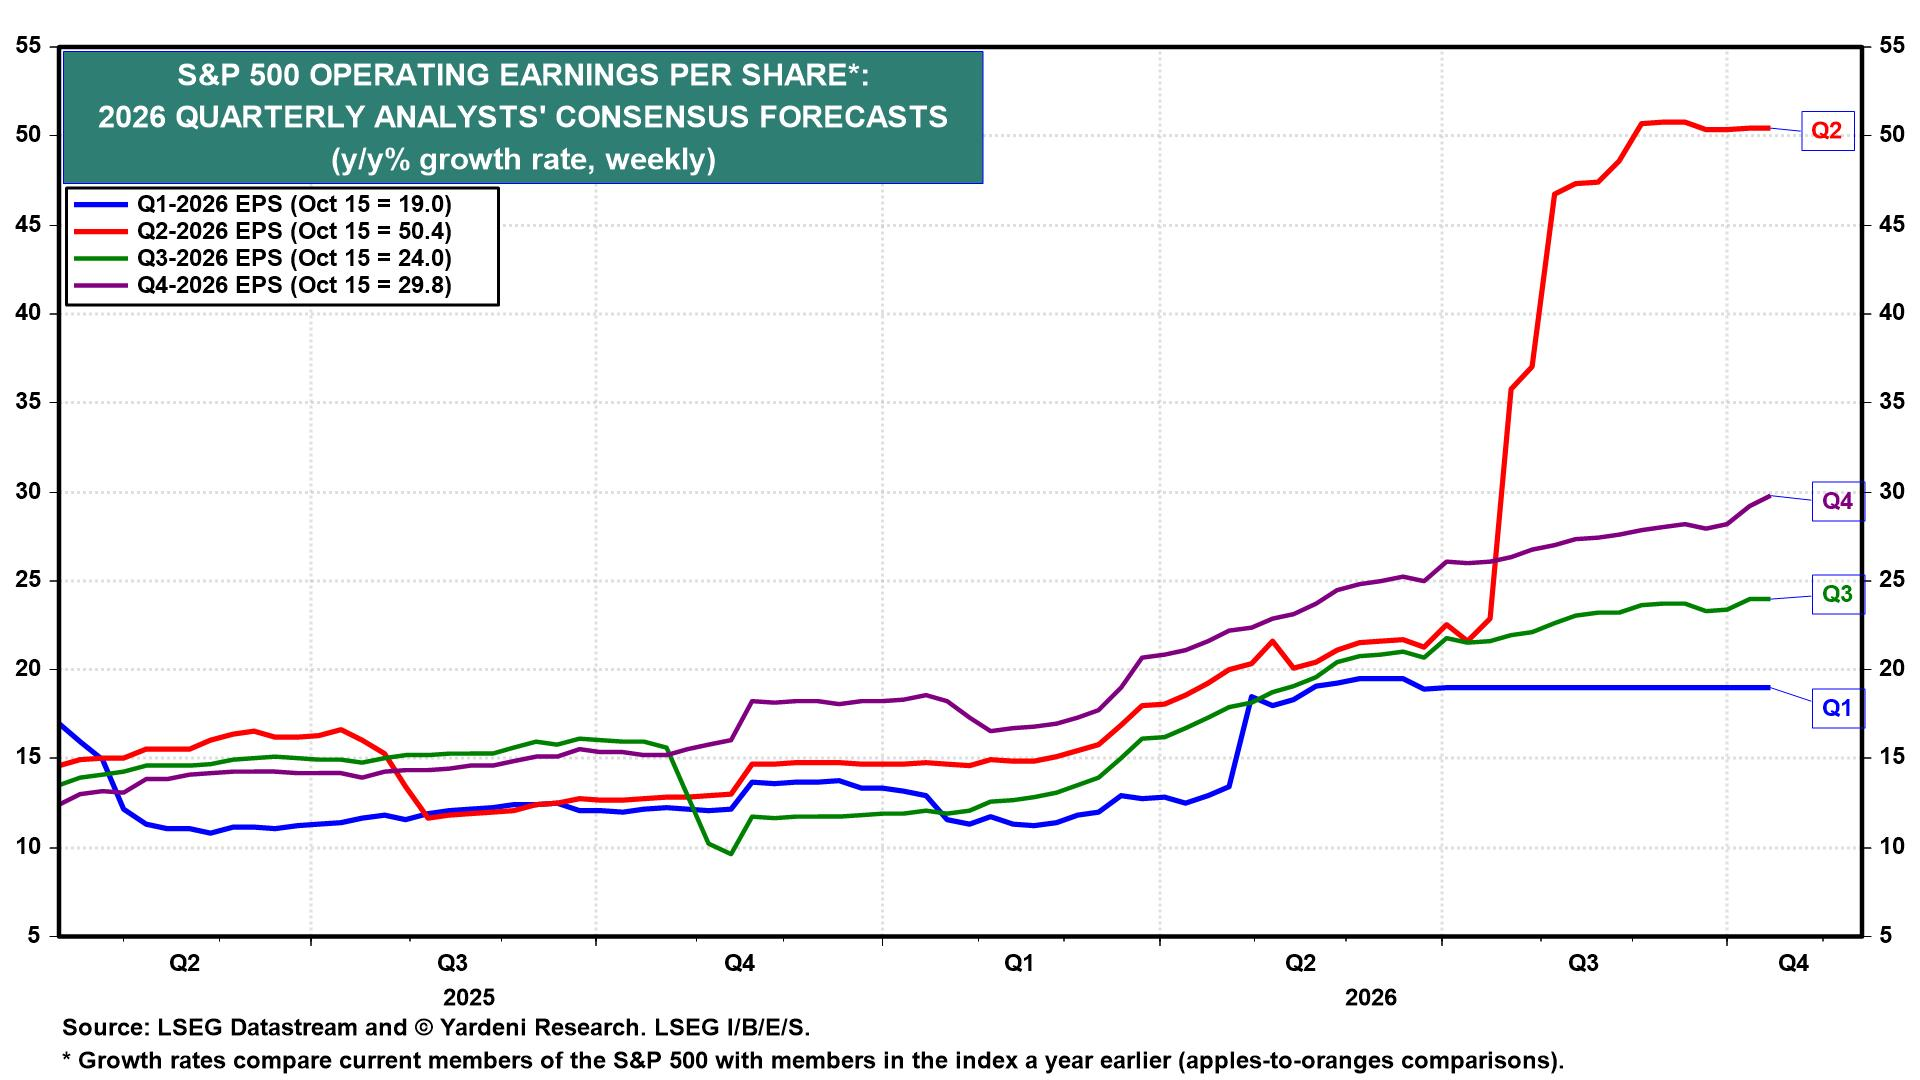
ASML and TSMC posted record Q3 results last week. ASML’s net sales rose to €11.7 billion from €9.3 billion in Q2, with the gross margin up to 57.5% from 54.0%. TSMC’s revenue jumped 50.9% y/y. Analysts’ consensus estimates imply Q3-2026 operating EPS growth for S&P 500 companies of 24.0% y/y (chart).
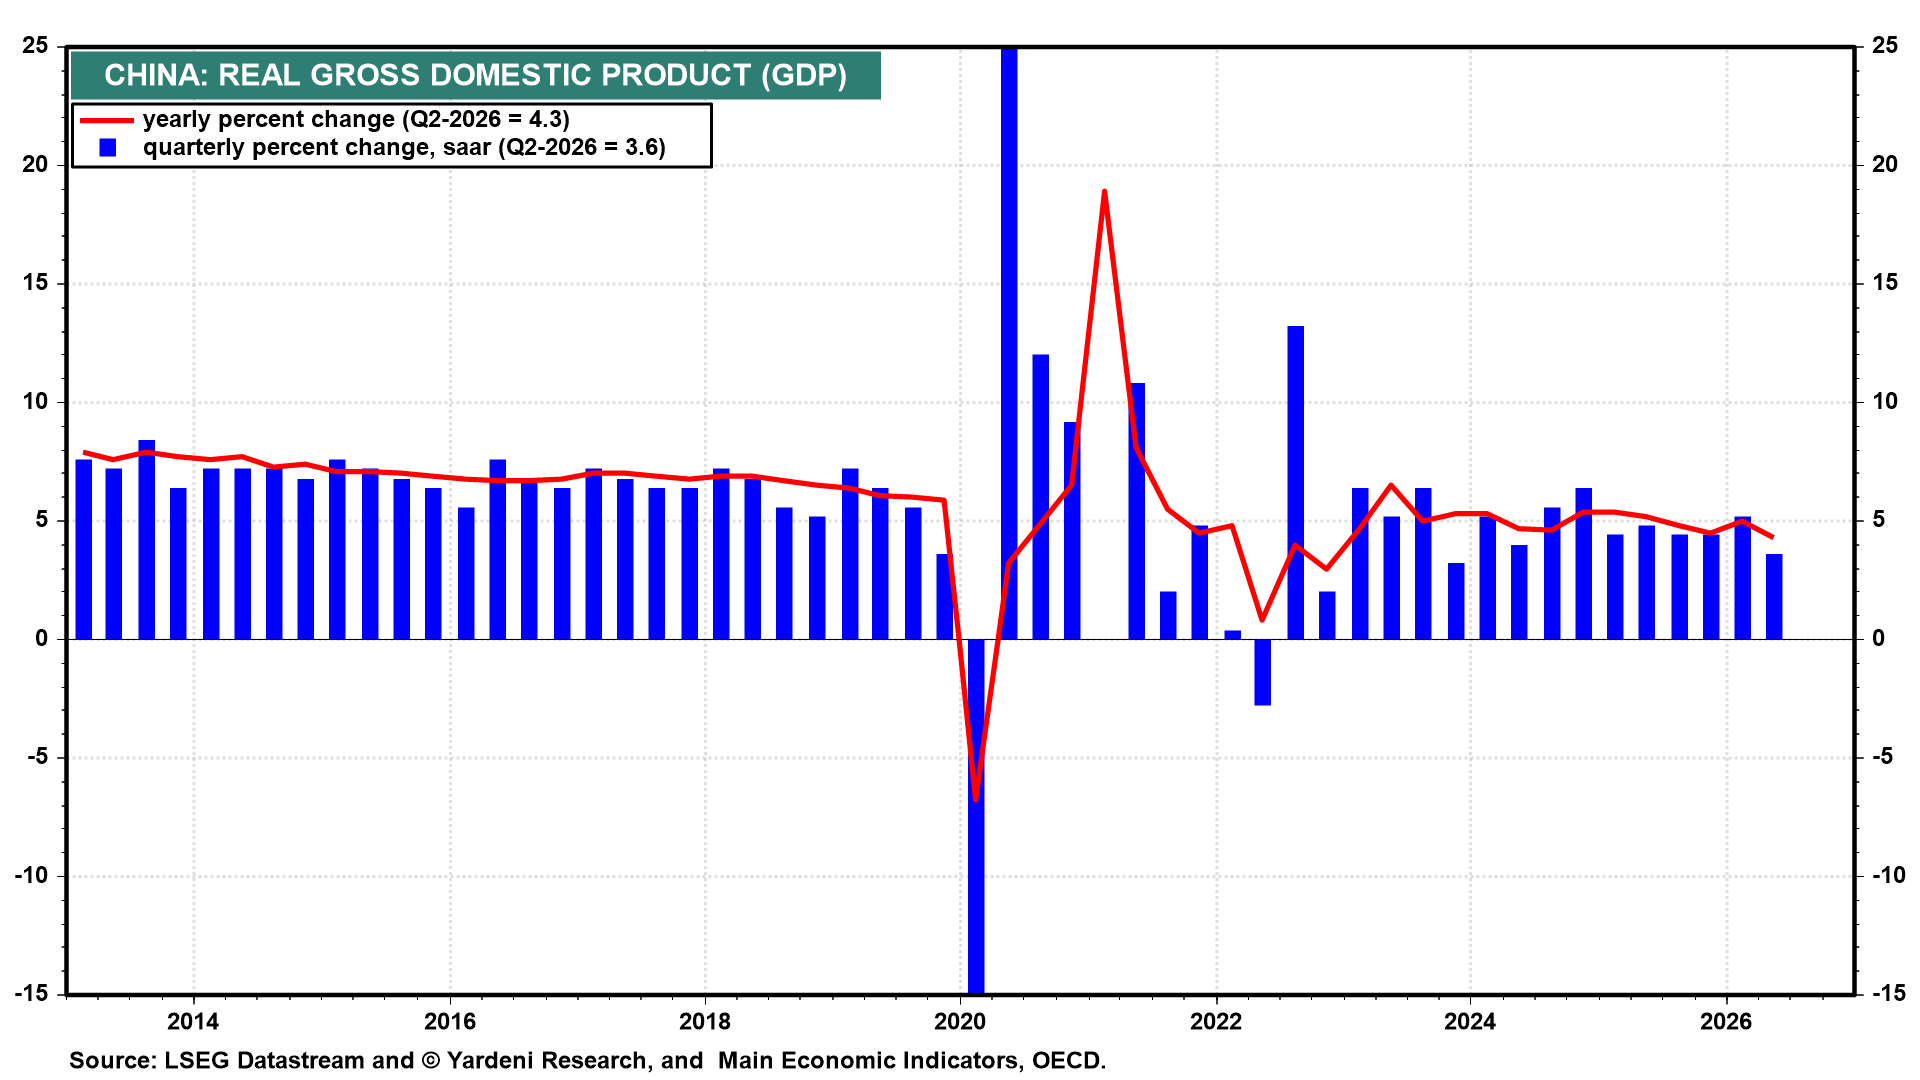
(4) Global. China’s Q3 GDP (Mon) follows Q2’s 4.3% y/y growth (chart). We expect a moderate pickup in activity. China’s unemployment rate for September is also due, following August’s 5.2% rate.
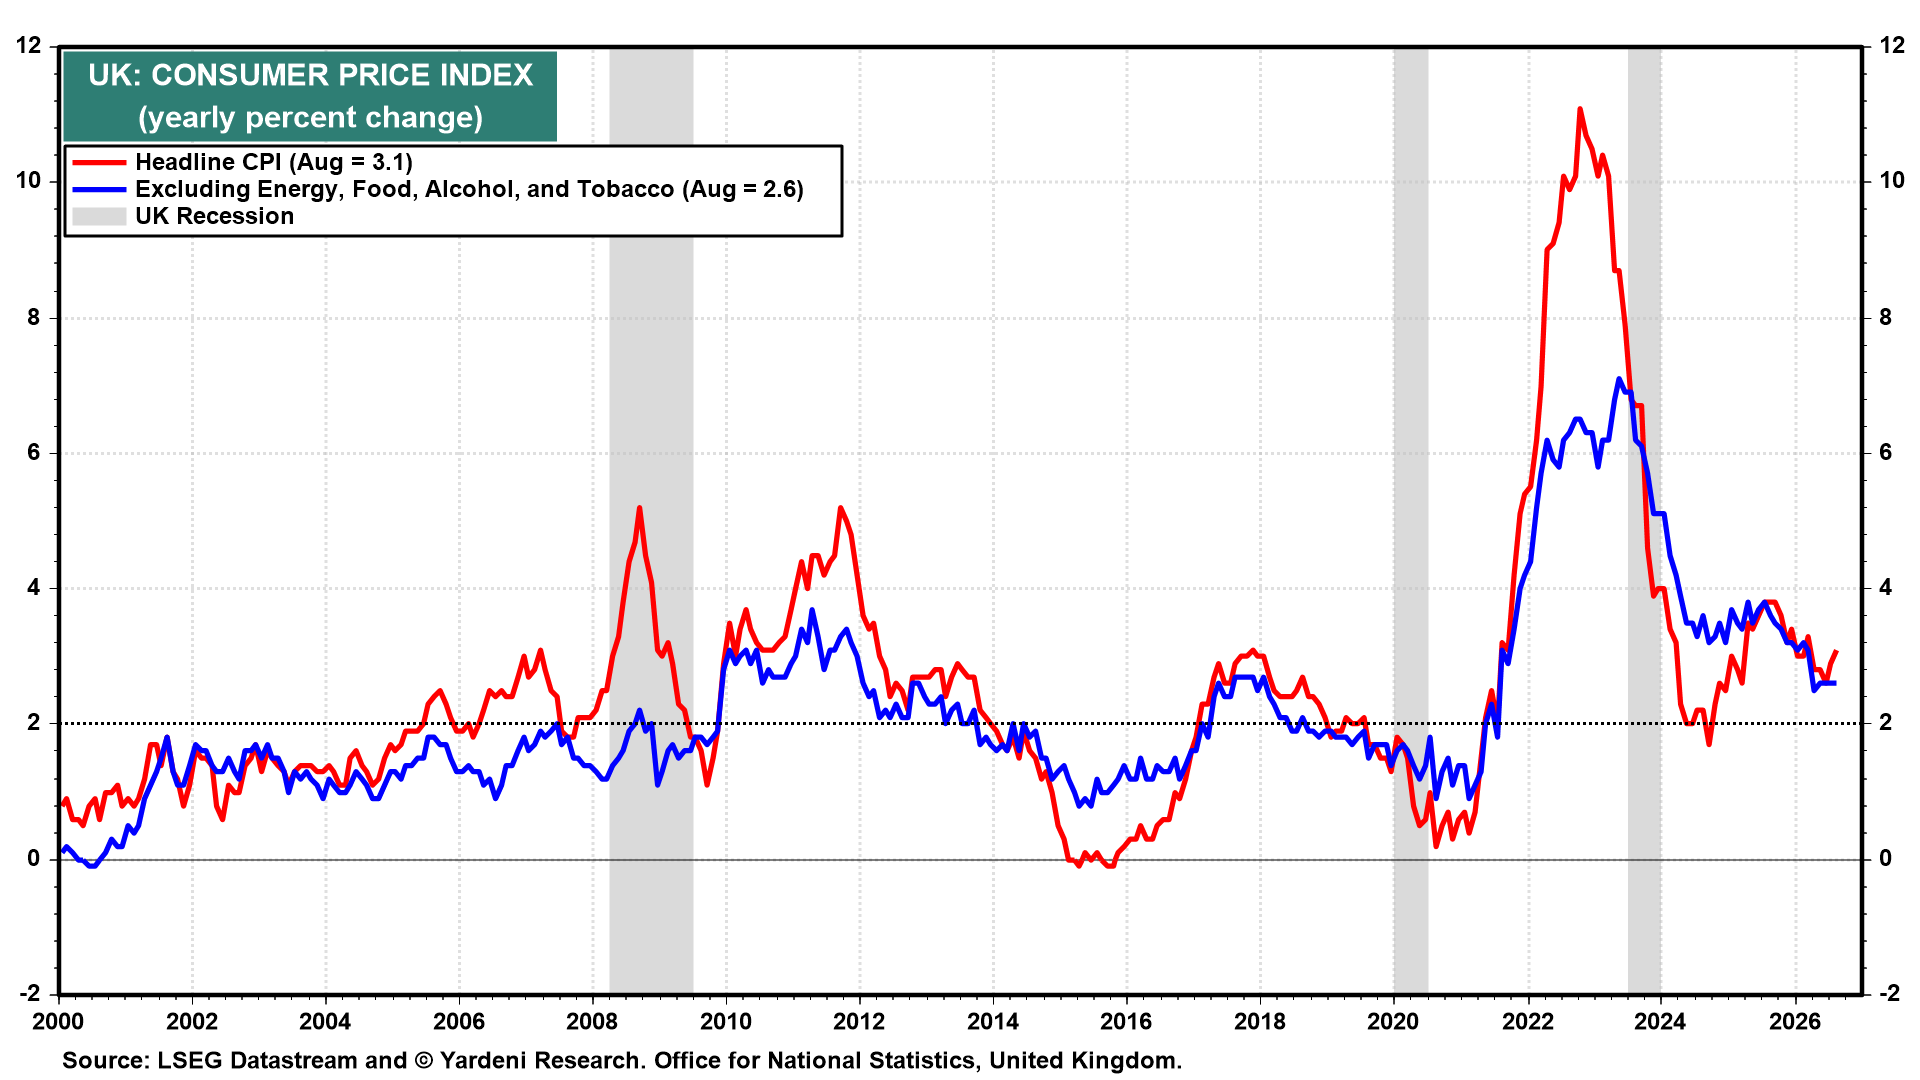
UK CPI (Wed) for September follows August’s 3.1% y/y headline and 2.6% core (chart). Rising energy and input costs point to a further pickup, with the input PPI up 8.2% y/y in Q2. Bank of England Governor Andrew Bailey speaks later that day. UK labor market data (Tue) and PPI (Wed) are also due.
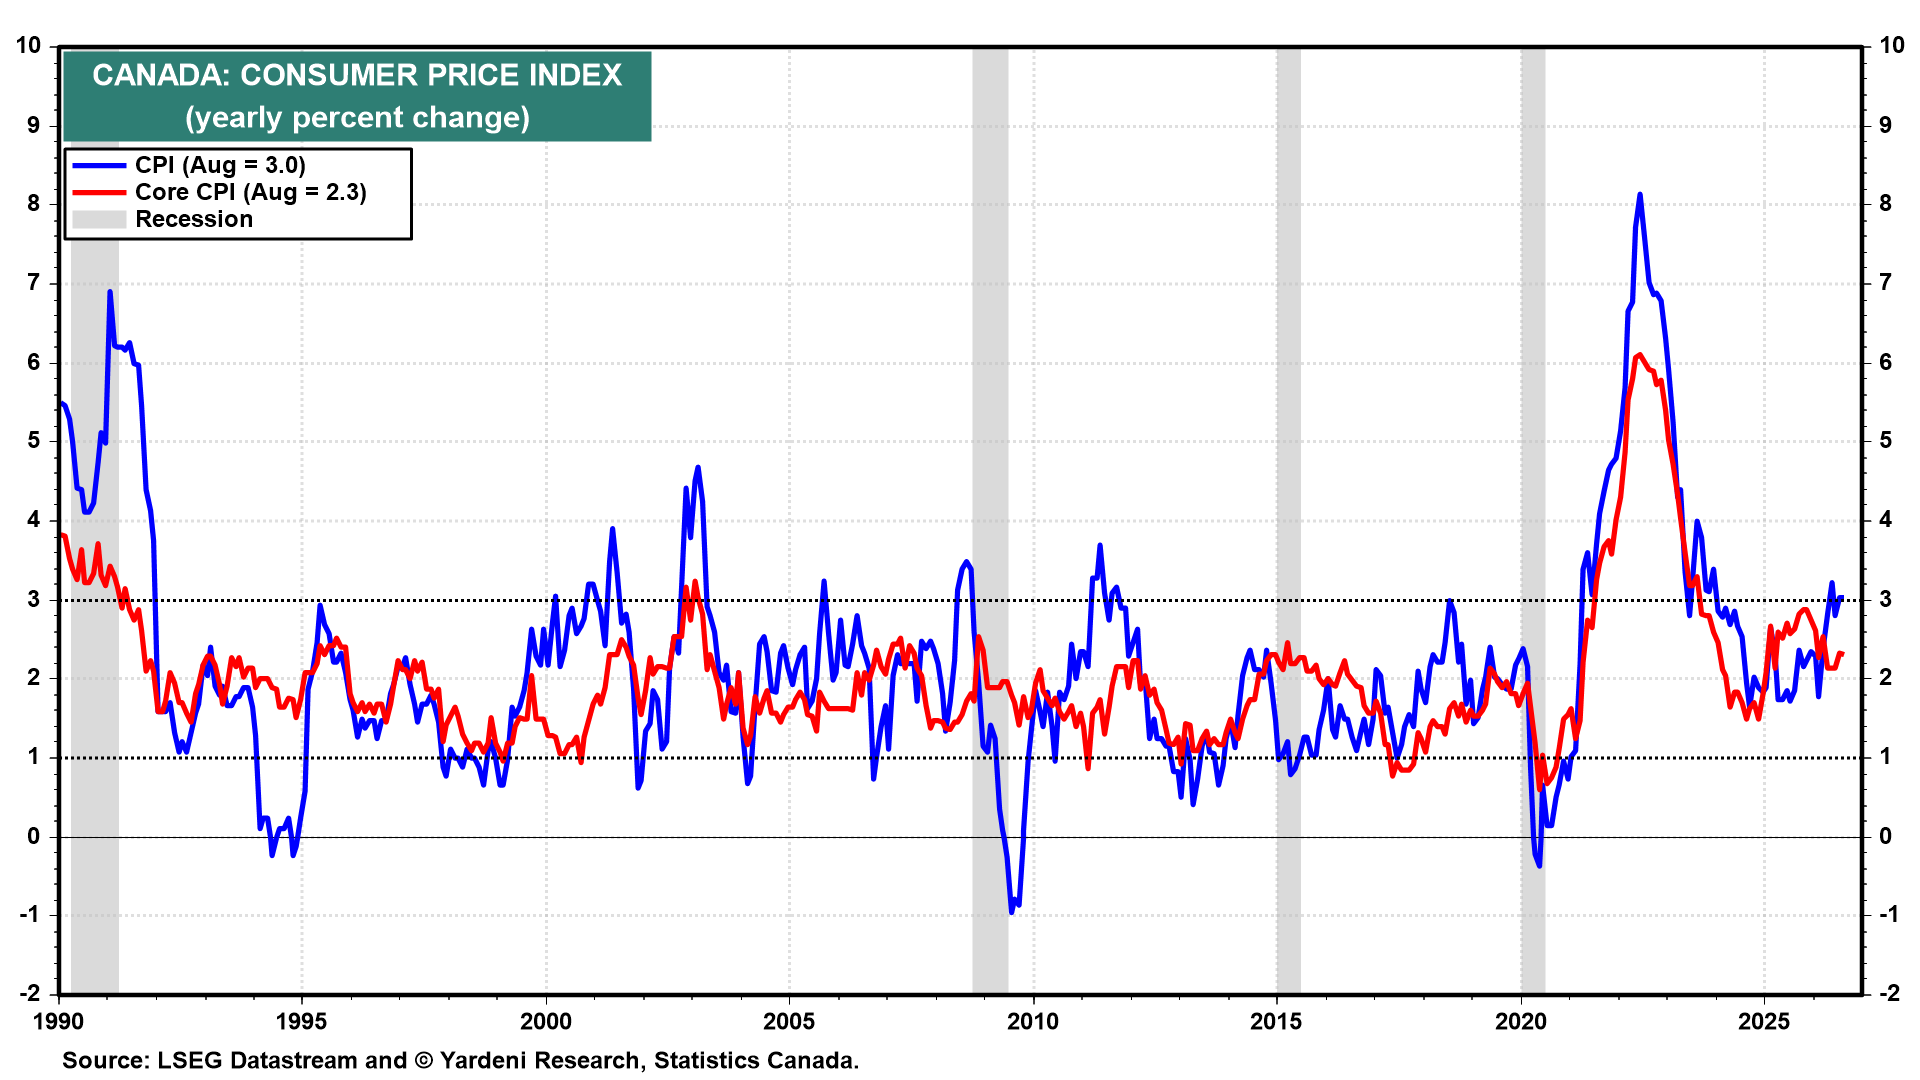
Canada’s CPI (Mon) for September follows August’s 3.0% y/y headline and 2.3% core (chart).