


I. Revenge of the Bond Vigilantes?
We still have a 70% subjective probability for our bullish base-case Roaring 2020s scenario. The remaining 30% covers all the possible bearish scenarios. We monitor those possibilities closely with our Worry List. Our main worry right now is the significant rise in bond yields worldwide this year (chart).
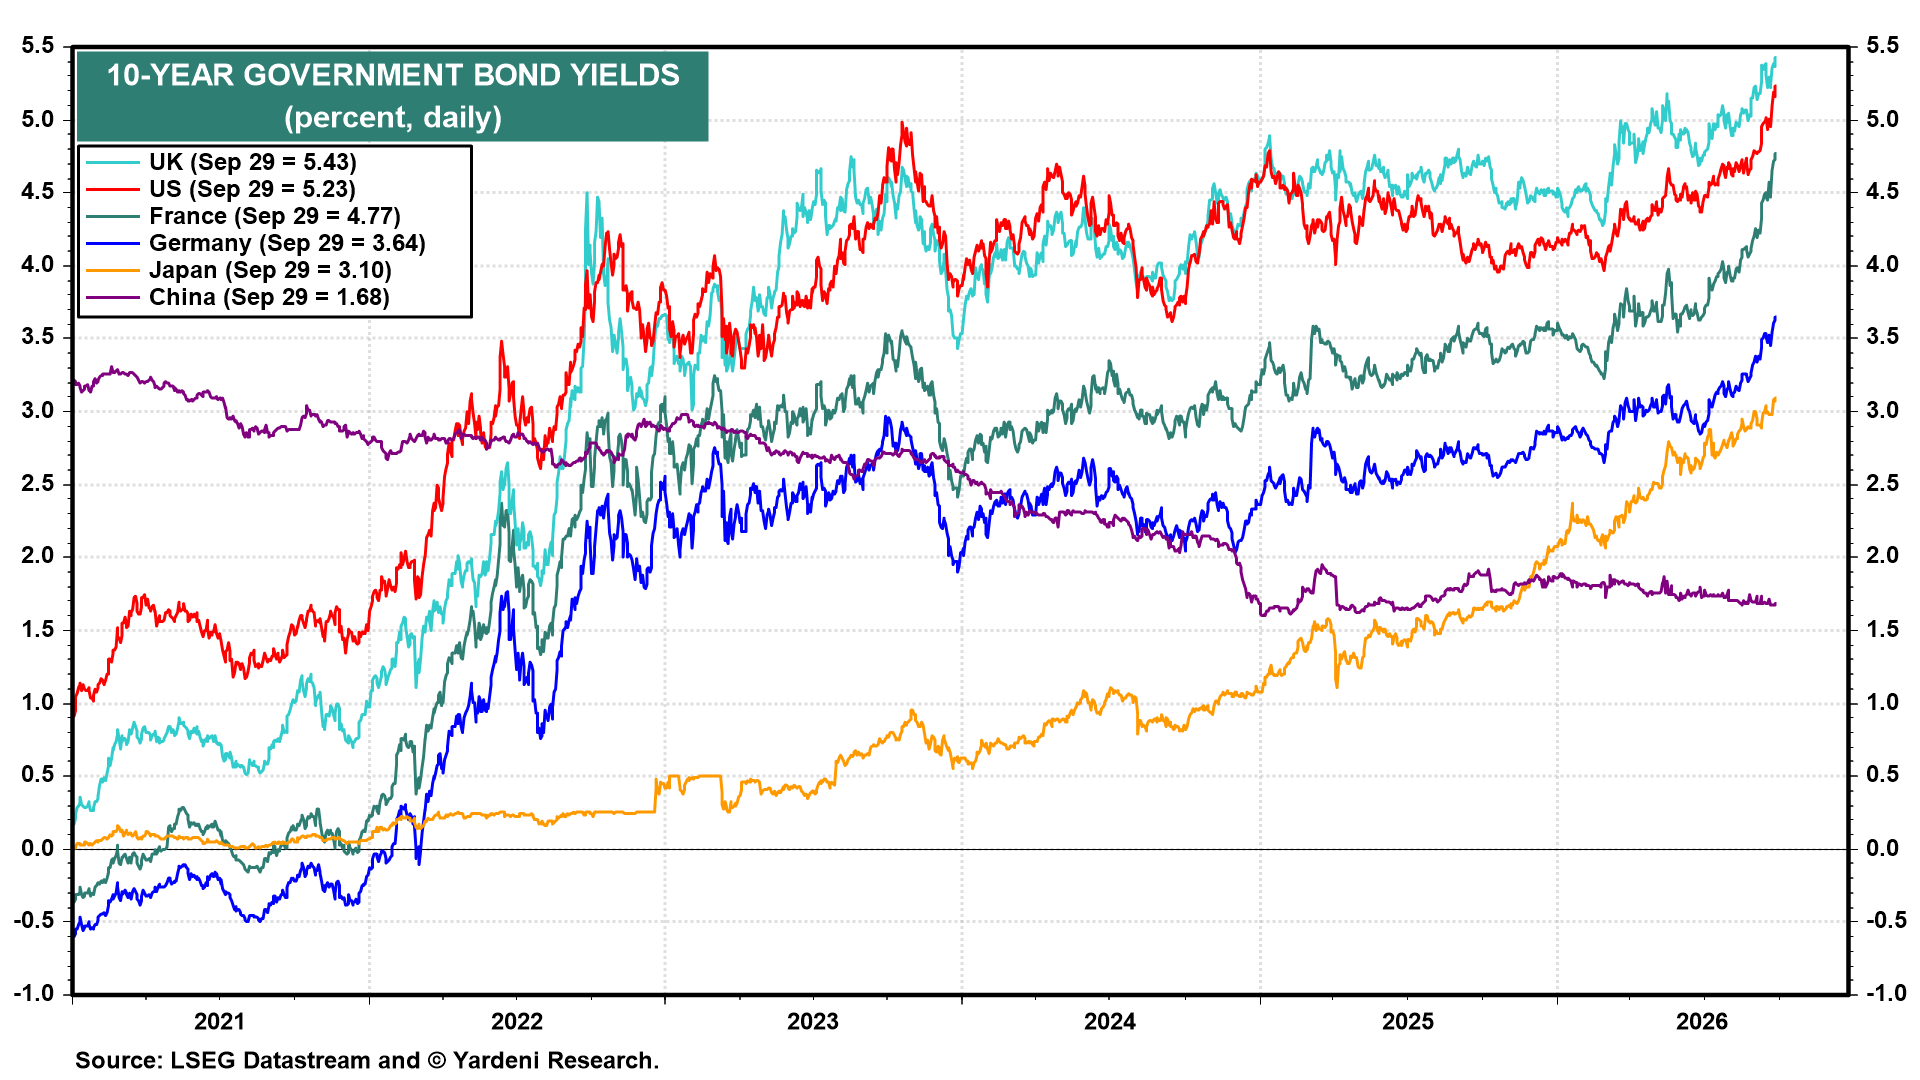
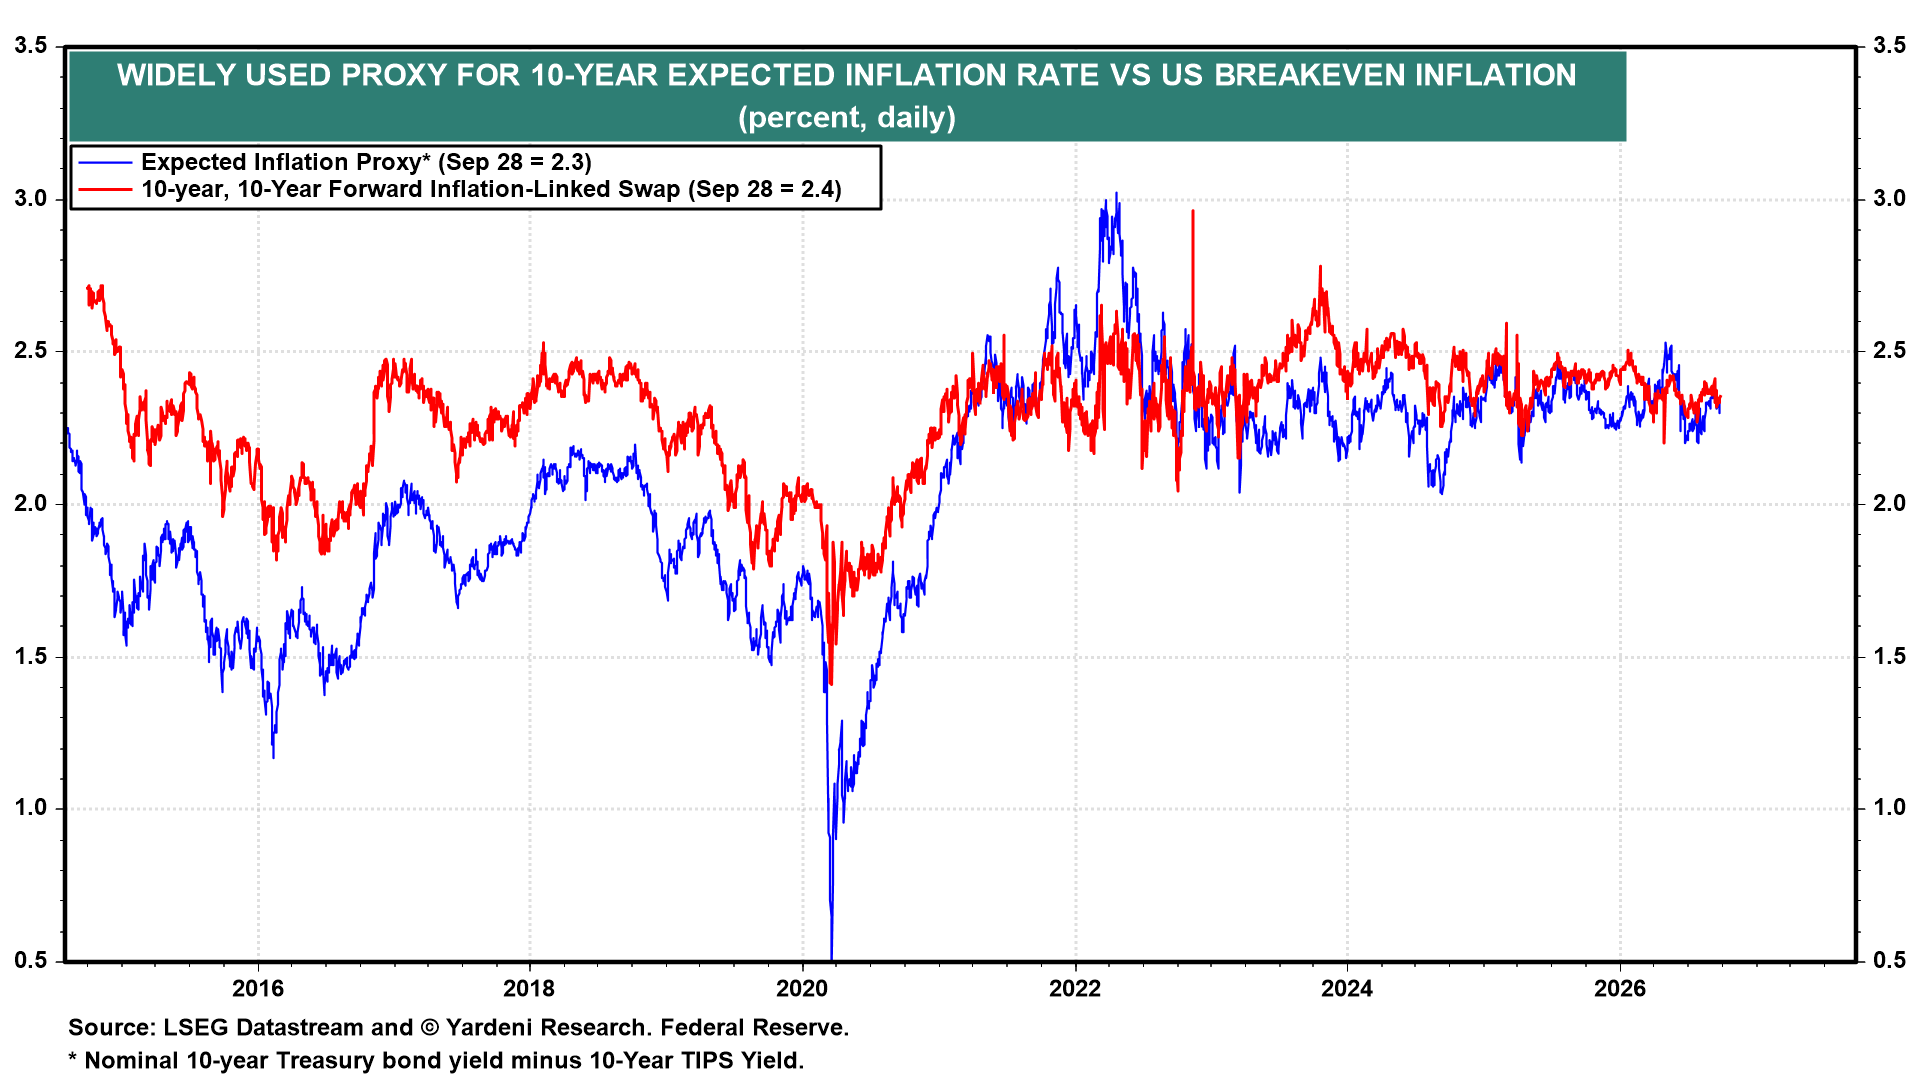
The higher global bond yields may be due to higher inflation, driven by the jump in oil prices following the Middle East war that began in late February. That's not confirmed by US breakeven inflation rates, which remain surprisingly subdued (chart)! Nevertheless, when the war ends, oil prices should drop sharply, lowering bond yields.
A more likely explanation for the global bond market rout is that the yen-carry trade is unwinding as the Bank of Japan (BOJ) raises its policy rate, forcing carry traders to sell government bonds they bought worldwide with proceeds from cheap yen loans (chart). This trade allowed many governments run budget deficits without putting upward pressure on their bond yields. Now, the chickens have come home to roost.
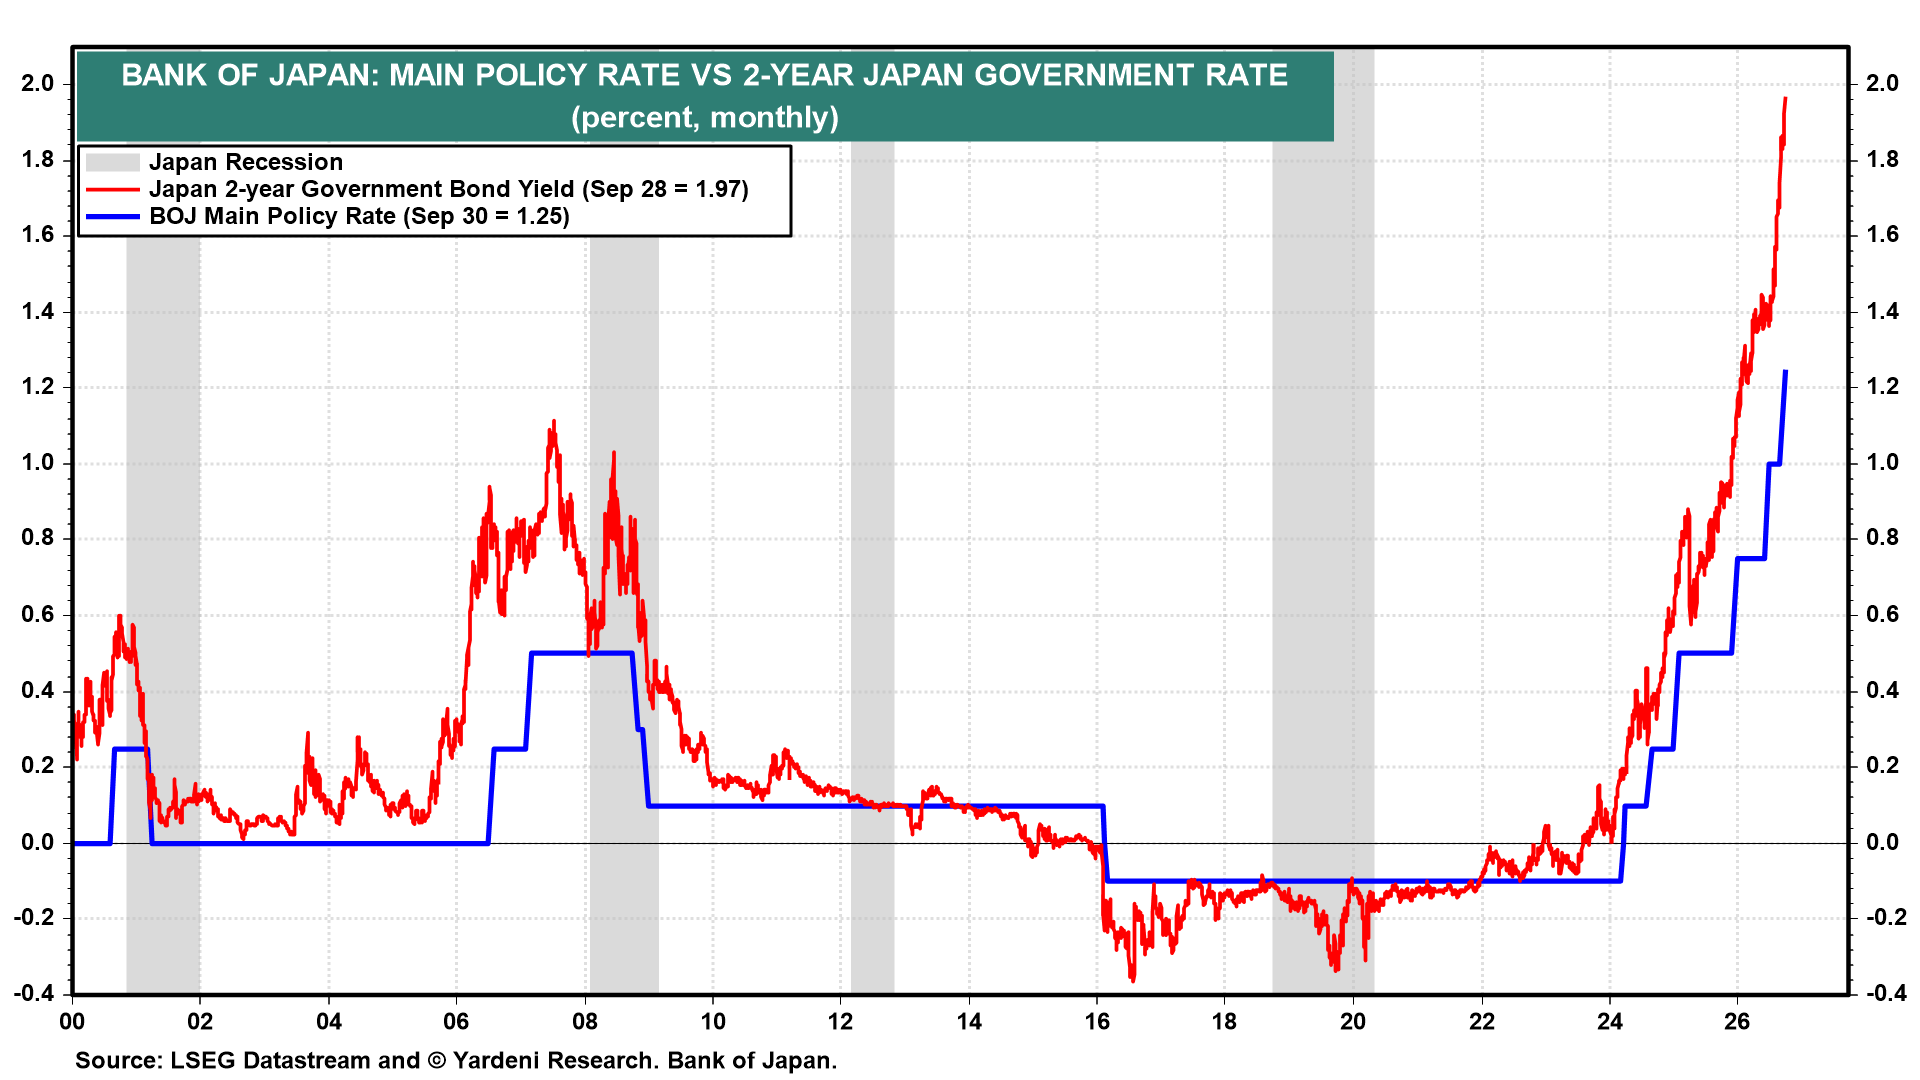
Governments ran large deficits and accumulated lots of debt when the BOJ and other major central banks kept interest rates abnormally low from the Great Financial Crisis through the Great Virus Crisis. The major central banks' quantitative easing policies rigged global bond markets. The Bond Vigilantes were subdued. Now, we may be witnessing the Revenge of the Bond Vigilantes.
II. Is Bessent getting twisted?
