


I. Bonds
We've all been suffering from AI fatigue for a while. The daily news about it has been head-spinning. We've been warned that AI is a bubble that will burst, just as the late-1990s tech bubble led to the Tech Wreck in the early 2000s. Analogies to the credit excesses of the Great Financial Crisis have also been proffered. Last week's rout in AI-related stocks convinced the naysayers that the AI bubble is bursting, just as they’ve long predicted it would.
Our happier spin is that the Bond Vigilantes are now doing a good job of regulating and allocating capital to the AI ecosystem. Credit-quality spreads are widening to reflect the riskiness of the bonds issued by some of the dodgier AI-related borrowers like CoreWeave and Oracle. The rapidly rising cost of credit for such borrowers should deflate the AI bubble without bursting it. If some AI-related credits do blow up, the Godfathers of the AI mafia (along with their protectors in the government) will clean up the mess. As in "The Godfather II," Michael Corleone has too much at stake to let his brother Fredo screw up the family business.
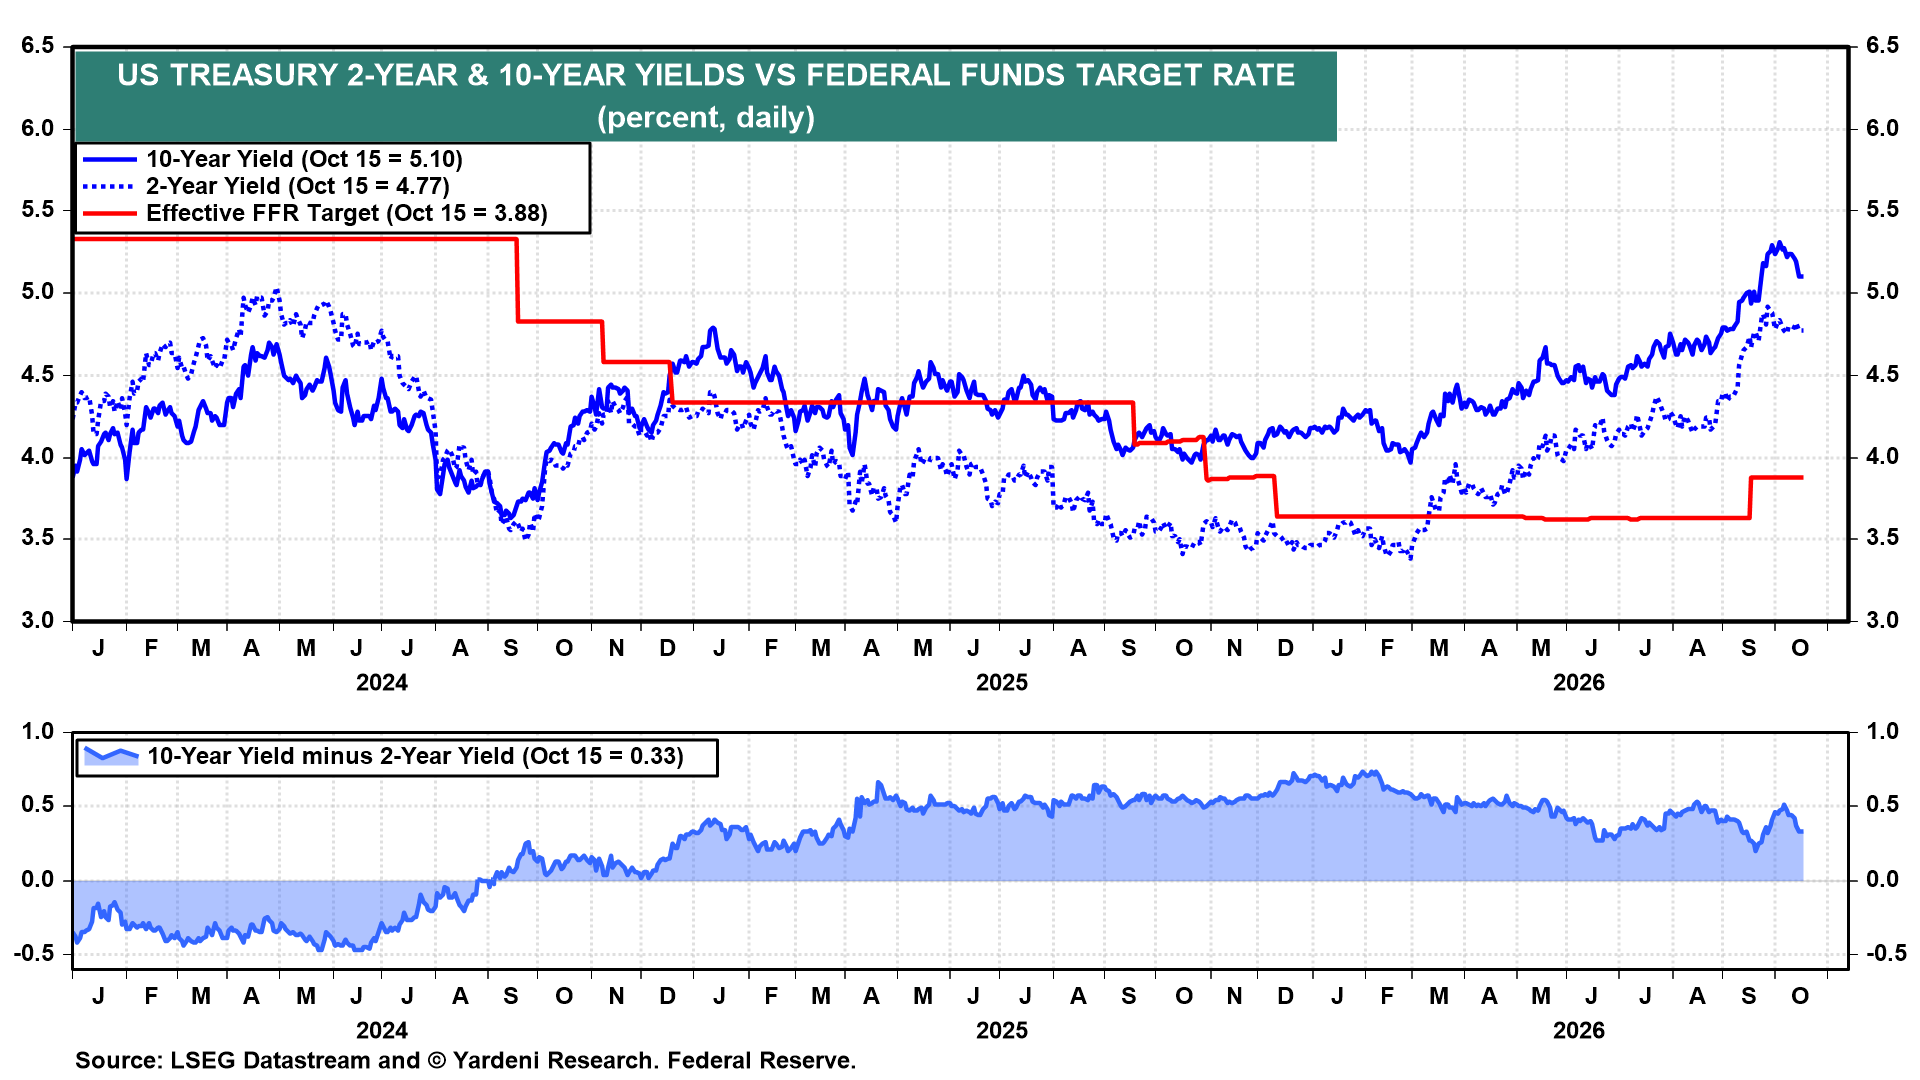
Meanwhile, the rout in the AI corporate bond market has triggered a flight to quality and safety that has stopped the rout in the US Treasury bond market (chart). This confirms our thesis that the recent rise in US bond yields mostly reflects better-than-expected economic growth. Tougher credit conditions in the AI corporate bond market should curb some of the AI excesses. However, we doubt this will trigger an economy-wide credit crunch or a recession. We aren't convinced that it will slow capital spending much, since labor and materials shortages, along with public NIMBY pushback, have already slowed the pace of data center construction.
II. S&P Earnings
