I. Blue skies ahead for earnings?
We are now seven years into our Roaring 2020s thesis, which remains our base case for the rest of the decade, and it has played out very well so far. When we first introduced the idea in August 2020, the prospect of another Roaring '20s sounded a bit delusional. We argued that, as in the 1920s, rapidly proliferating technologies would drive a productivity boom that would support stronger economic growth while containing inflation, boosting real wages, widening profit margins, and lifting corporate earnings.
Since the beginning of the current decade, the economy's resilience has repeatedly defied the naysayers, as productivity growth has increased and corporate earnings have continued to climb. With only three full years left in the decade, one of the clearest manifestations of our Roaring 2020s thesis has been what we call FEMO, or Fabulous Earnings Momentum.
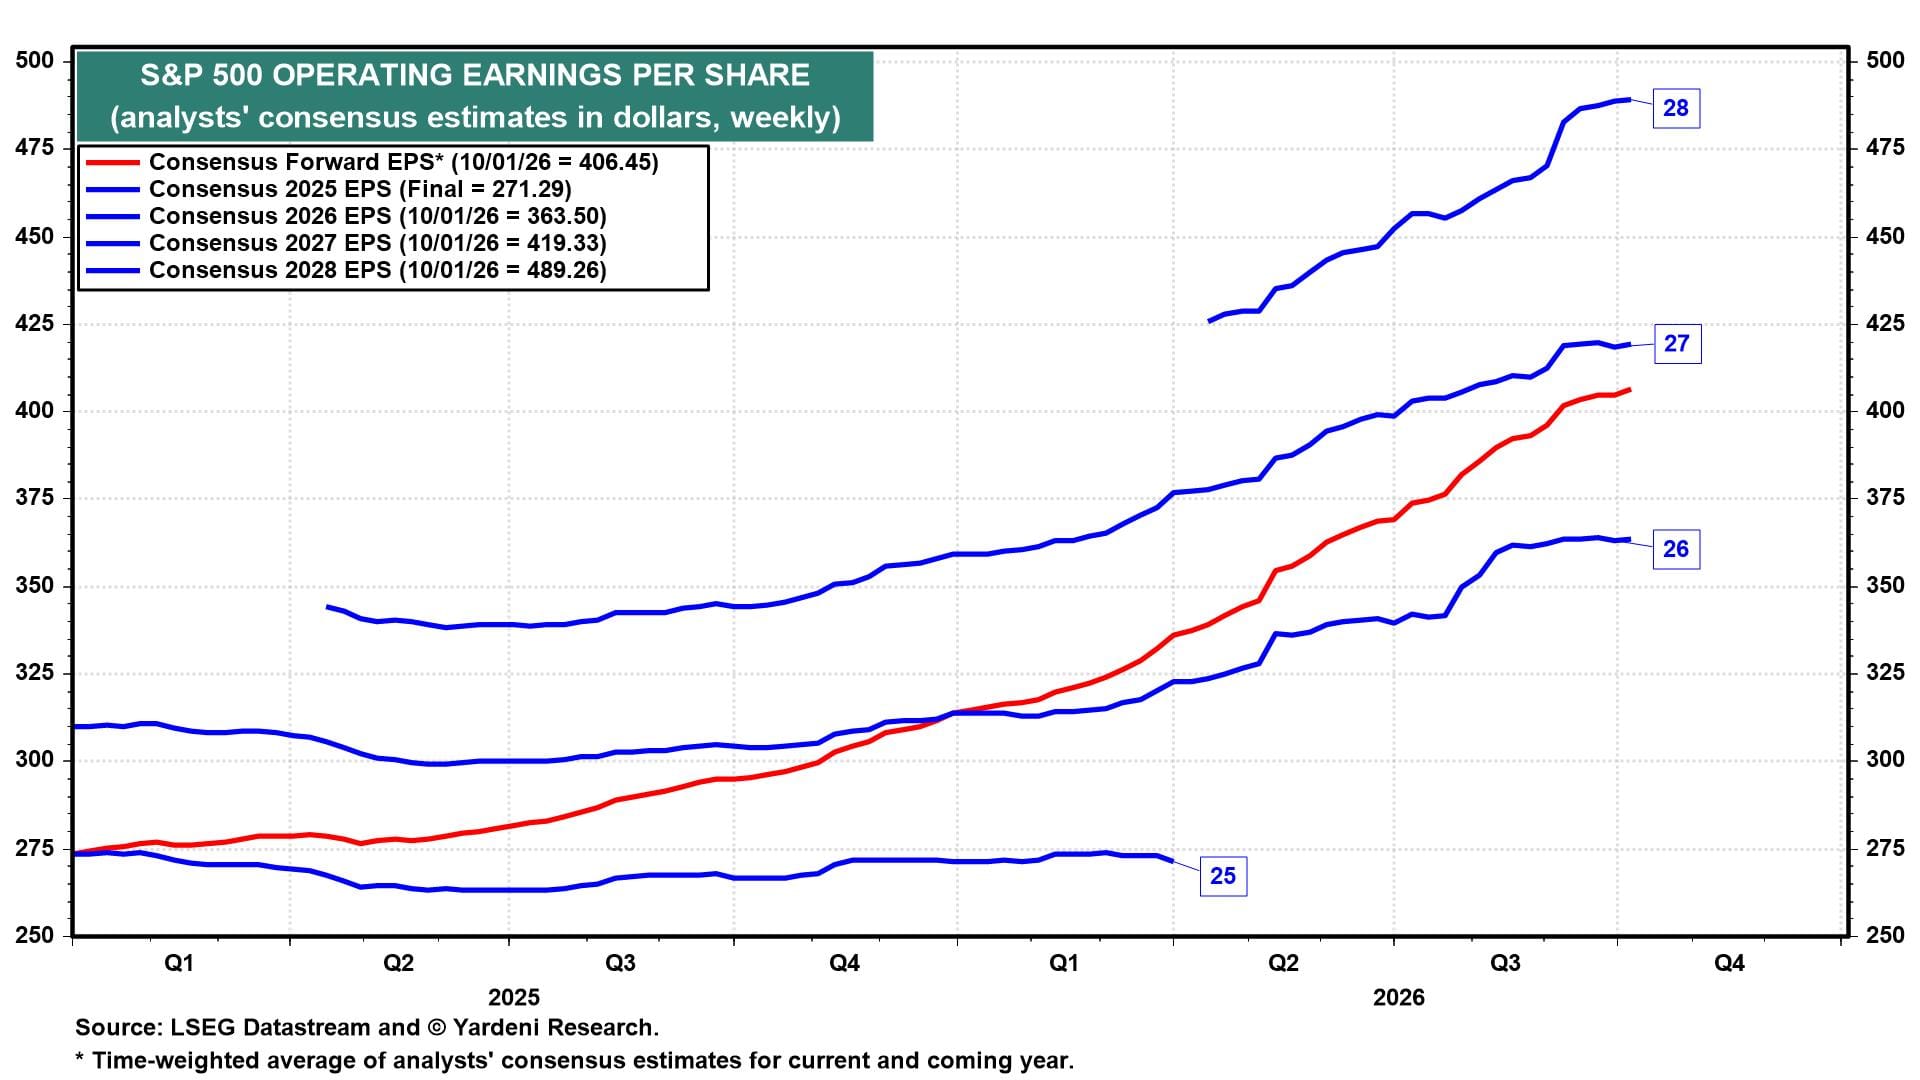
FEMO is clearly visible in industry analysts' earnings expectations. They currently expect S&P 500 operating earnings per share to rise to about $364 per share in 2026 and $419 in 2027, implying growth of roughly 15% in both years (chart). Toward the end of Q3 each year, we add another year to our Earnings Squiggles framework. This year’s addition is 2028, with earnings projected to rise another 17% that year to about $489 per share.
For now, the analysts are more bullish than we are about earnings prospects over the remainder of the decade. We are projecting $450 per share in 2028, $475 in 2029, and $500 in 2030. If they are right, our S&P 500 target of 10,000 will be achieved well before the end of 2029!