


I. Micron and the AI Trade
Memory has become one of the biggest beneficiaries of the AI spending boom. Micron’s stock, for example, is up 273.2% ytd, second only to SanDisk among the semiconductor companies. We have been bullish on memory, and Micron’s fiscal Q4-2026 results reinforced our view. Revenue surged 379% y/y to a record $54.2 billion, above the $50.8 billion consensus. Adjusted EPS of $33.42 topped management’s guidance range. Gross margins widened to 87% as DRAM and NAND prices surged.
The outlook was even stronger. Micron guided fiscal Q1-2027 revenue to $61.5 billion, well above the roughly $57 billion analysts expected. Management expects memory supply-demand conditions to tighten further in 2027 and 2028, with more than 75% of fiscal 2027 output already committed. The company now has 26 long-term agreements (LTAs), up from 16 last quarter.
Many investors still view memory as a classic boom-bust commodity. Before the latest earnings report, Micron’s forward P/E was 6.8. The stock barely budged today following the company's gangbusters results (chart).
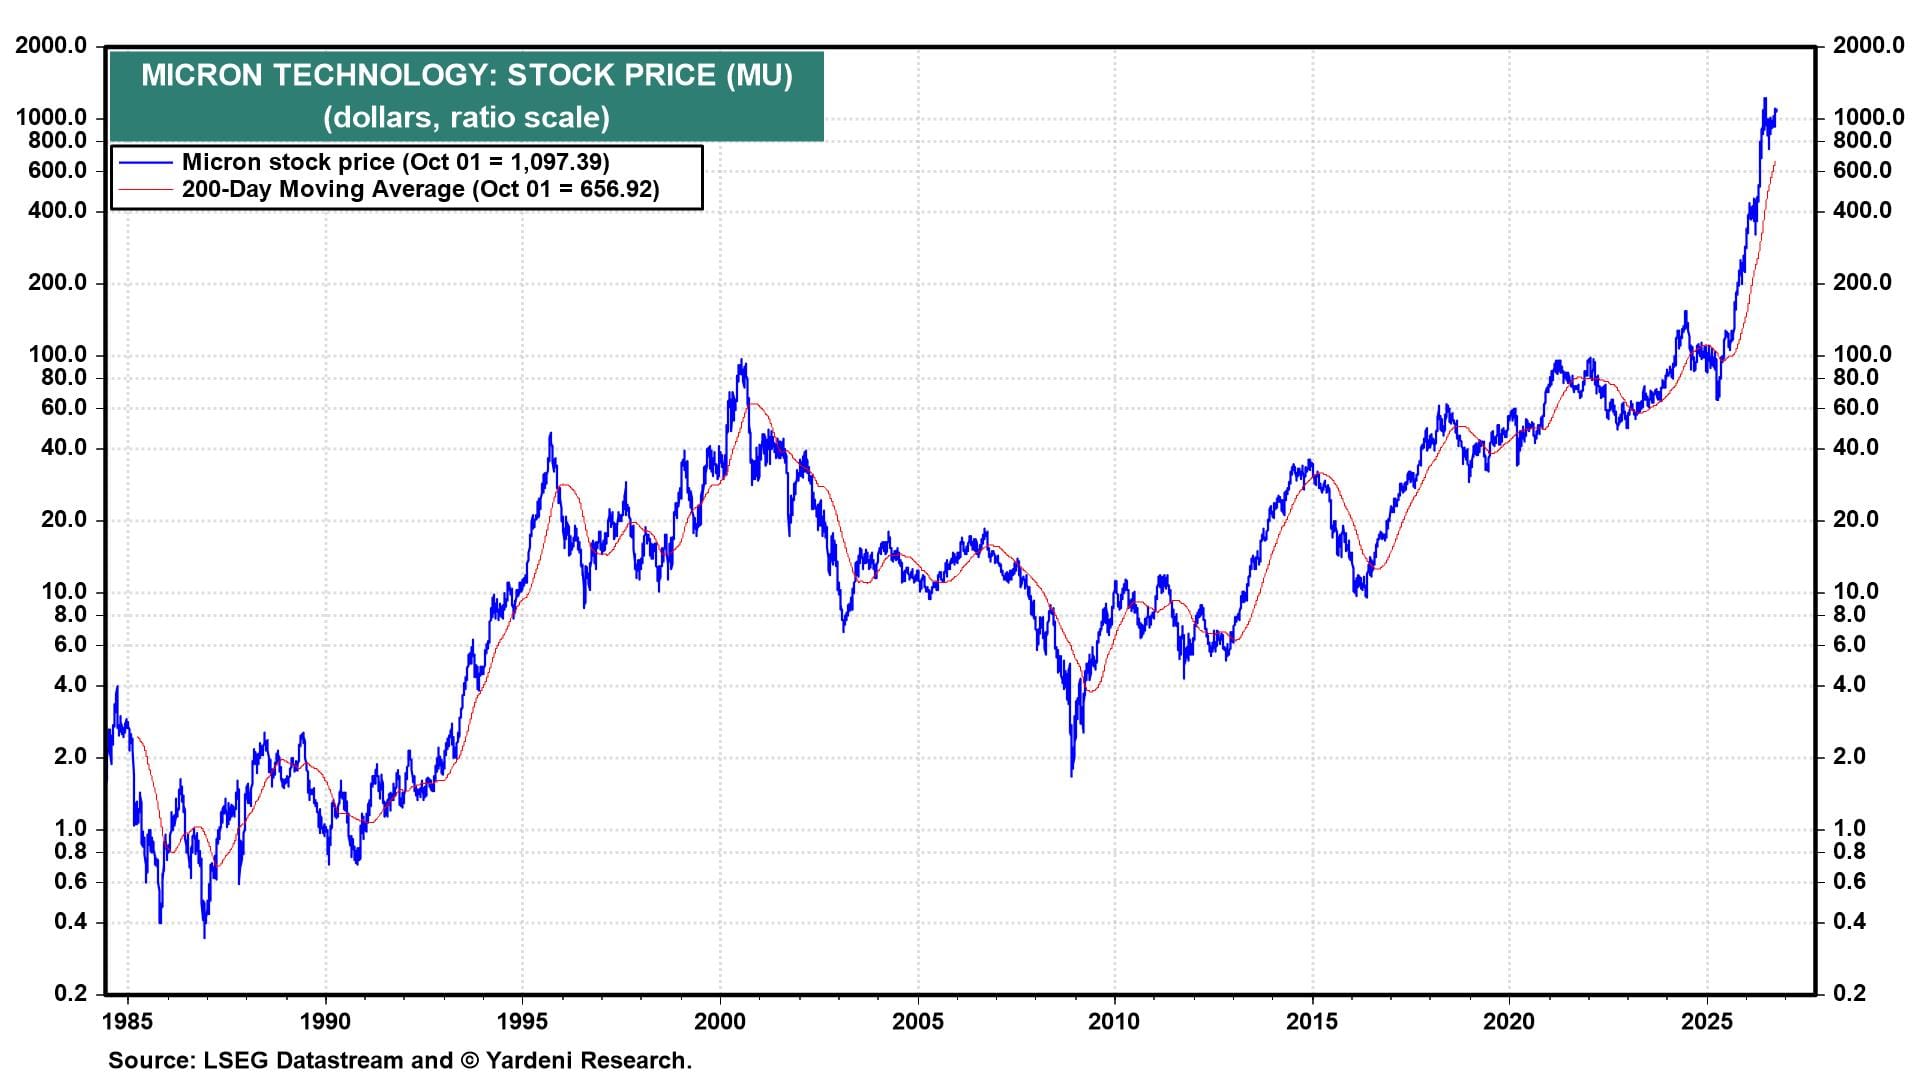
Micron’s results reinforce the case that the AI buildout still has plenty of runway. Hyperscalers continue to increase infrastructure spending. Indeed, Goldman Sachs recently raised its 2027 hyperscaler capex forecast to $1.2 trillion, roughly 50% above $750 billion this year.
II. "Growthflation"
