


I. Global Economy
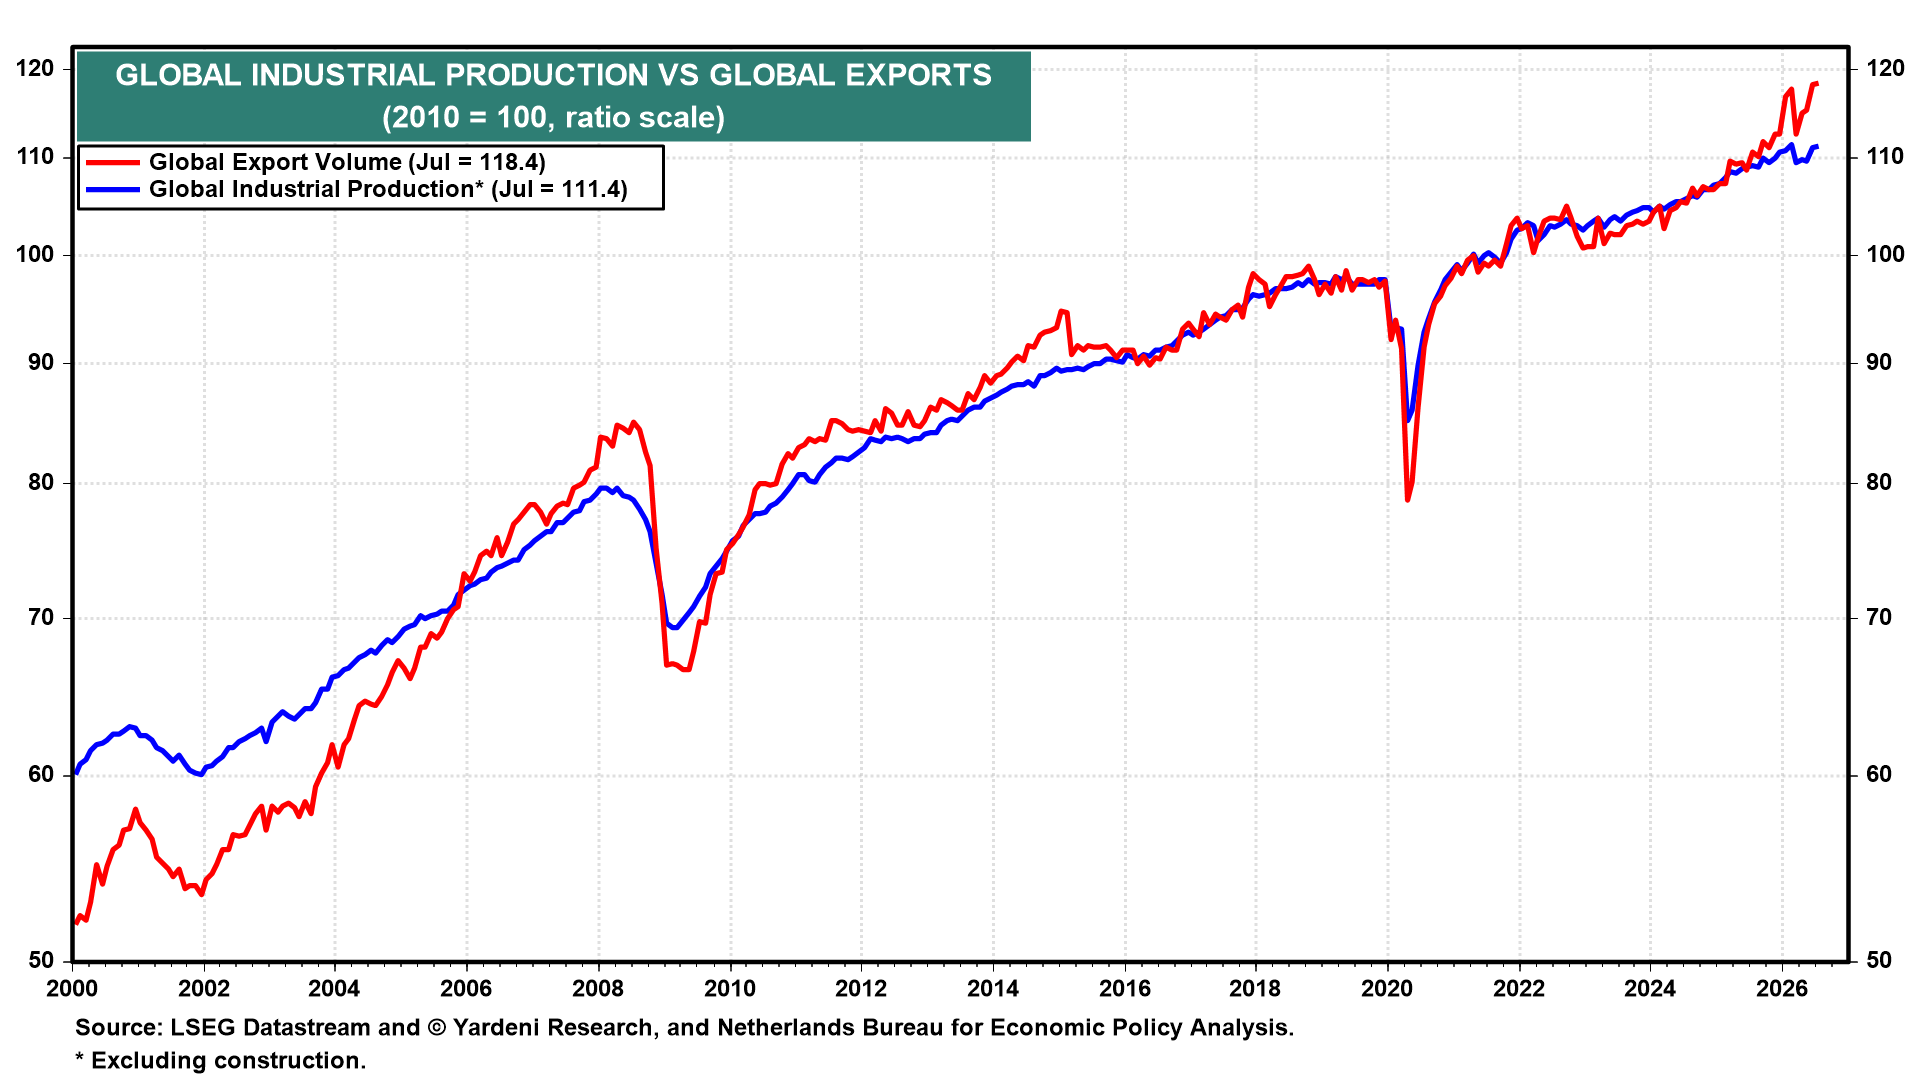
The global economy has been surprisingly resilient so far this year. There were dips earlier this year, when the Middle East war was in full swing; but in recent months, global industrial production and exports have rebounded to their record highs from before the war (chart).
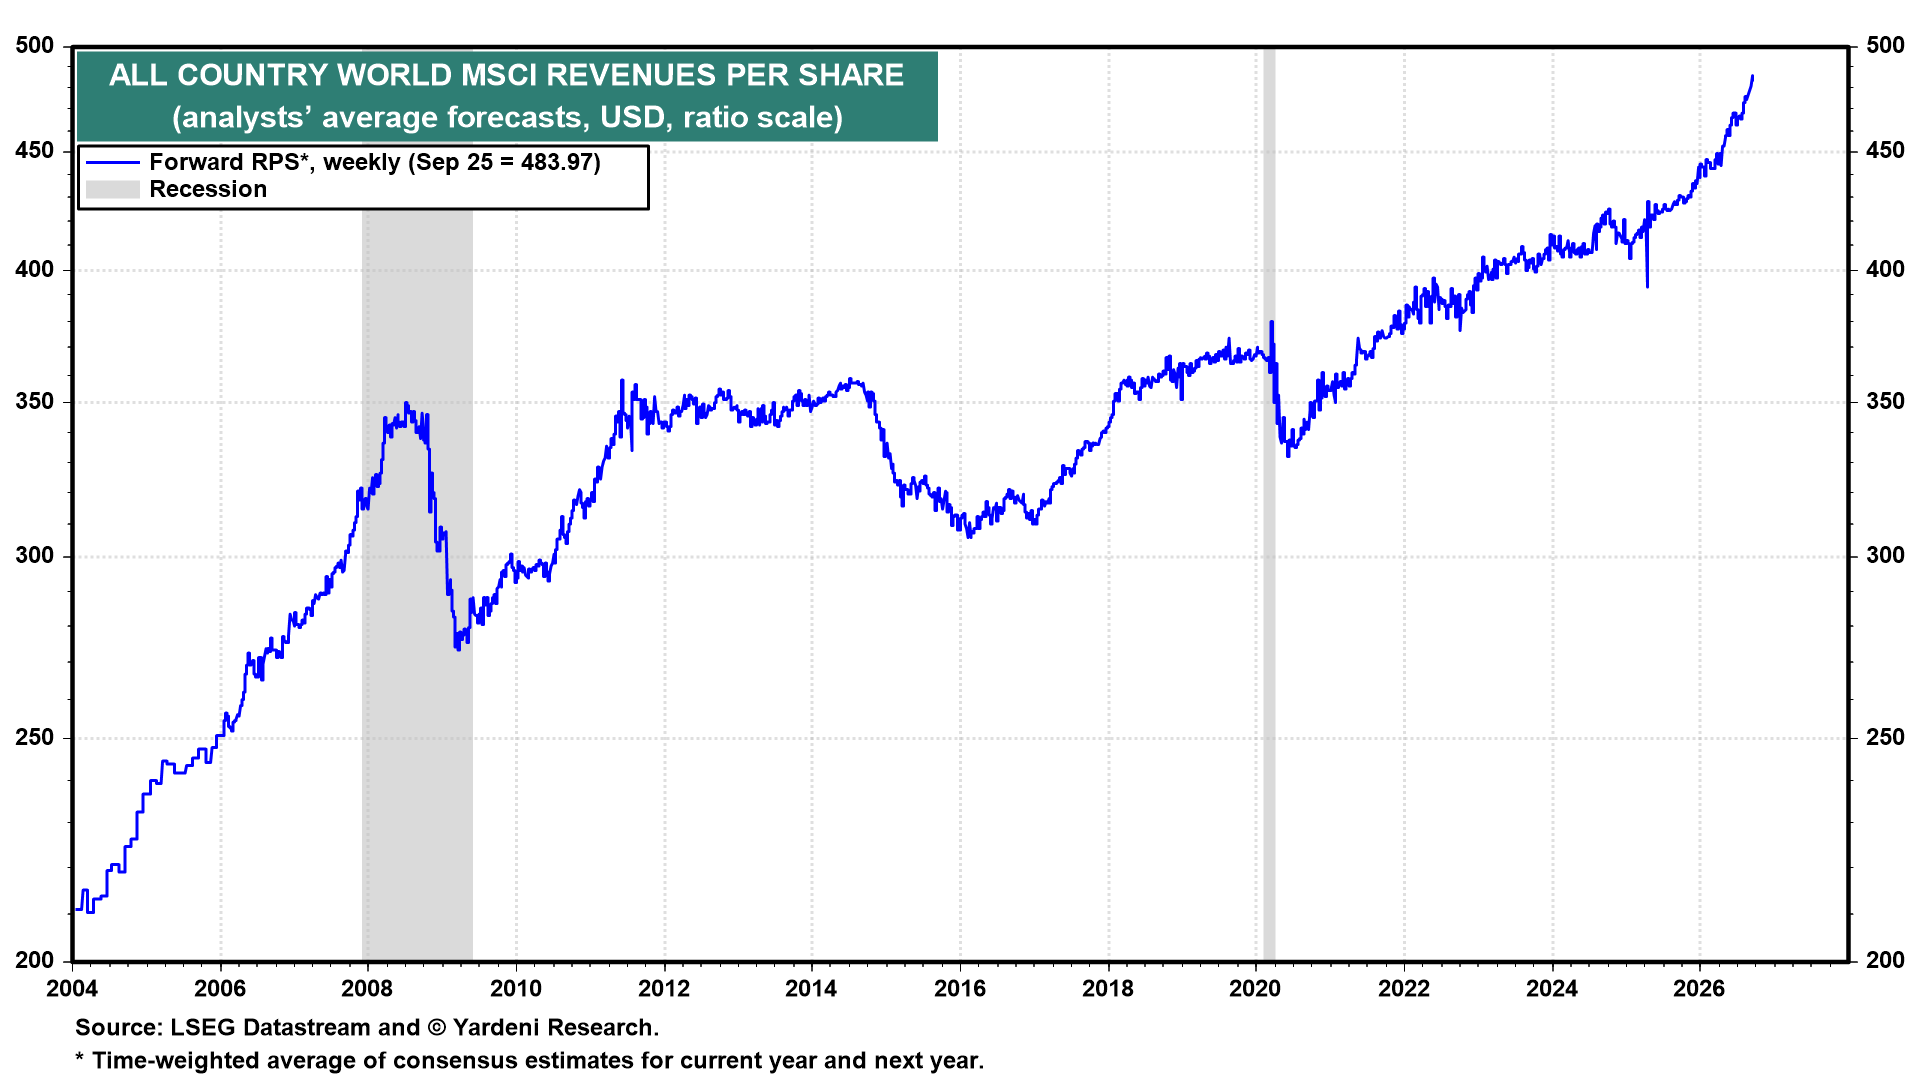
The All Country World MSCI forward revenues per share has continued to soar to record highs this year (chart).
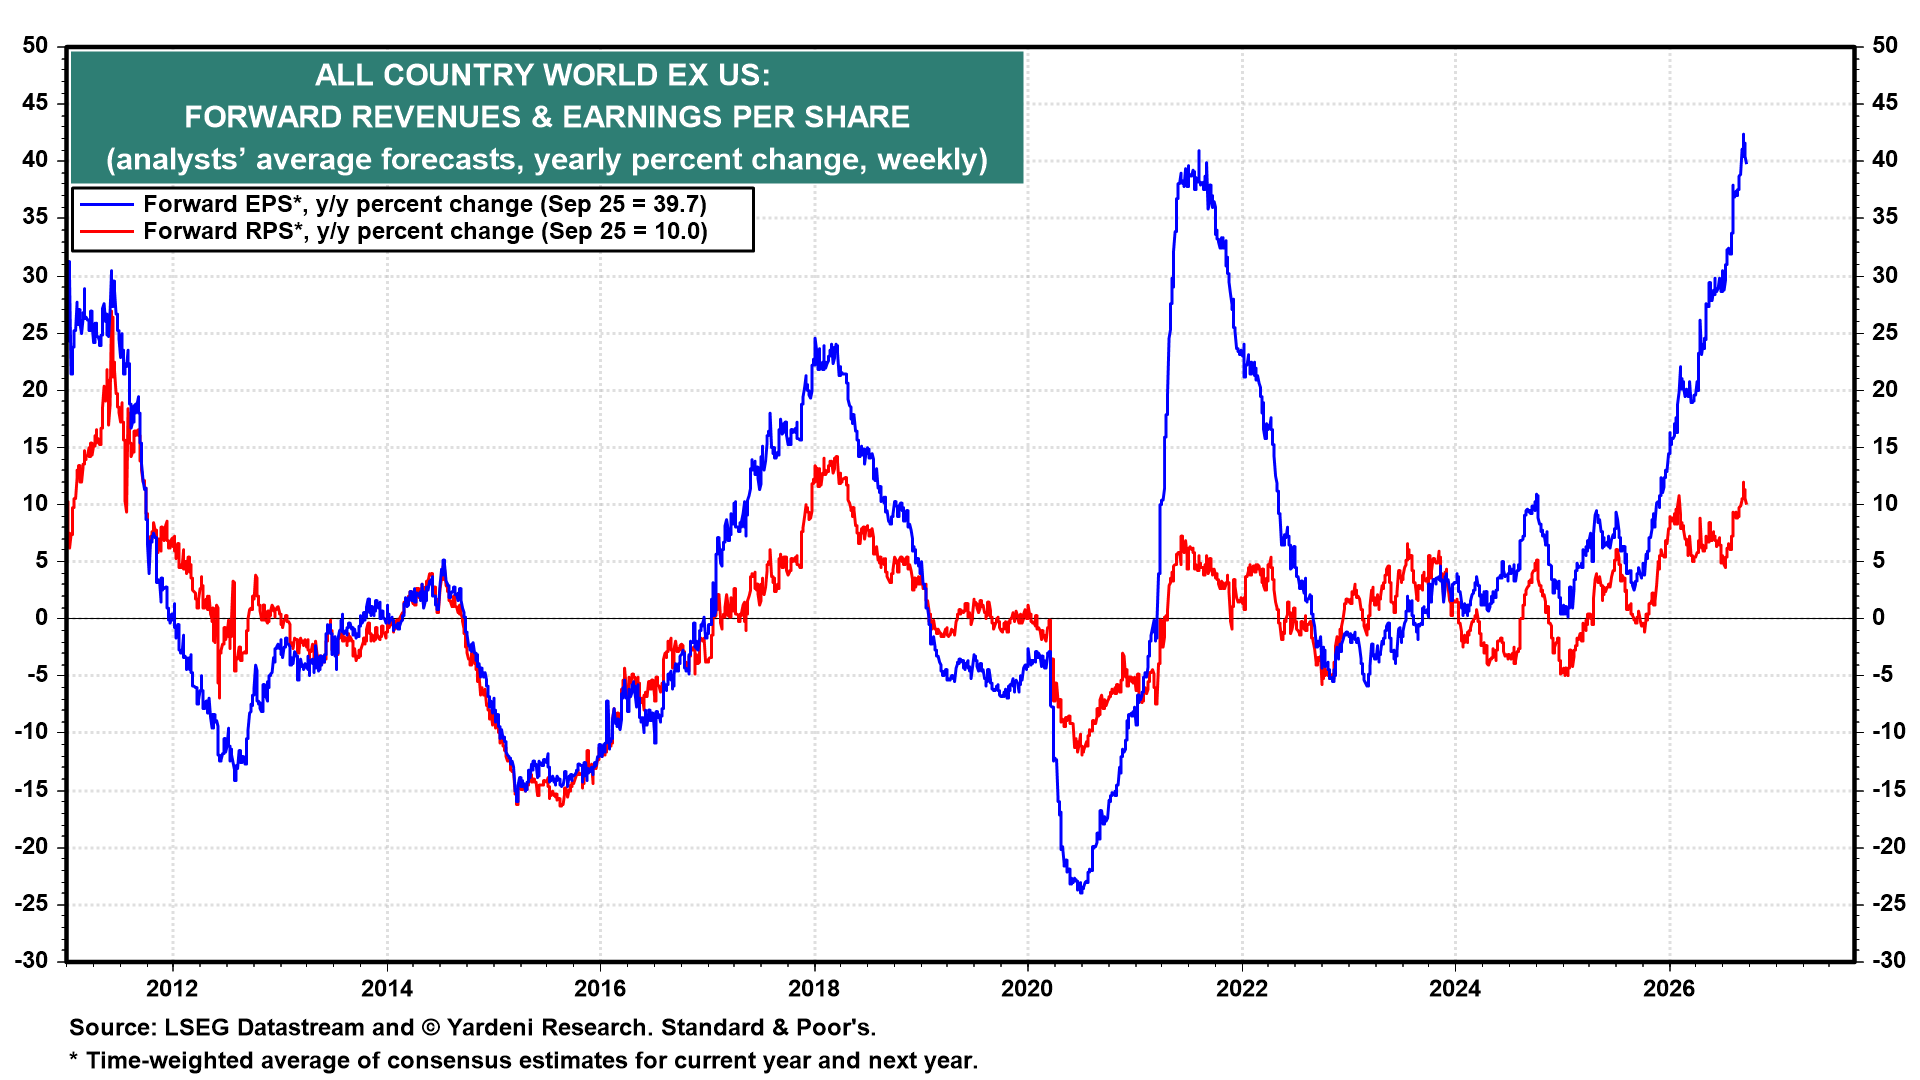
The All Country World ex-US MSCI is up a very solid 10.0% y/y, with forward earnings up a record 39.7% (chart).
II. Global Interest Rates
The significant increase in oil prices so far this year hasn't knocked the wind out of the global economy’s sails. The question is whether rapidly rising interest rates will do so. The rapid rise in 2-year government note yields worldwide signals that major central banks need to raise their policy rates further in response to the inflationary impact of higher-for-longer oil prices resulting from the recent re-escalation of the Middle East war (chart). Unfortunately, these higher rates also exacerbate the outlook for large government deficits worldwide.
A diplomatic settlement of the war would certainly help to bring down oil prices and interest rates. However, President Donald Trump has reportedly rejected an offer by Iran to reopen the Strait of Hormuz and end the conflict. He intends to resume bombing Iran after the midterm elections if Iran doesn't agree to dismantle its nuclear program. That means higher-for-longer oil prices, sticky inflation, and more central bank tightening.
